A Canadian Retirement Cash Flow Plan That Balances Spending, Taxes and Benefits
Retirement Planning Dale Roberts 516 reads
A sample plan for a 60-year-old Canadian retiree shows how withdrawals, delayed benefits and flexible spending can shape retirement income.
A retirement plan has to do more than show whether the money lasts. It also needs to connect spending today with taxable withdrawals, future pension income and the possibility of higher costs later in life. A sample plan for Herman, a recently retired 60-year-old in Canada, shows how those pieces can be mapped over time—and where the assumptions matter.
Herman’s starting point
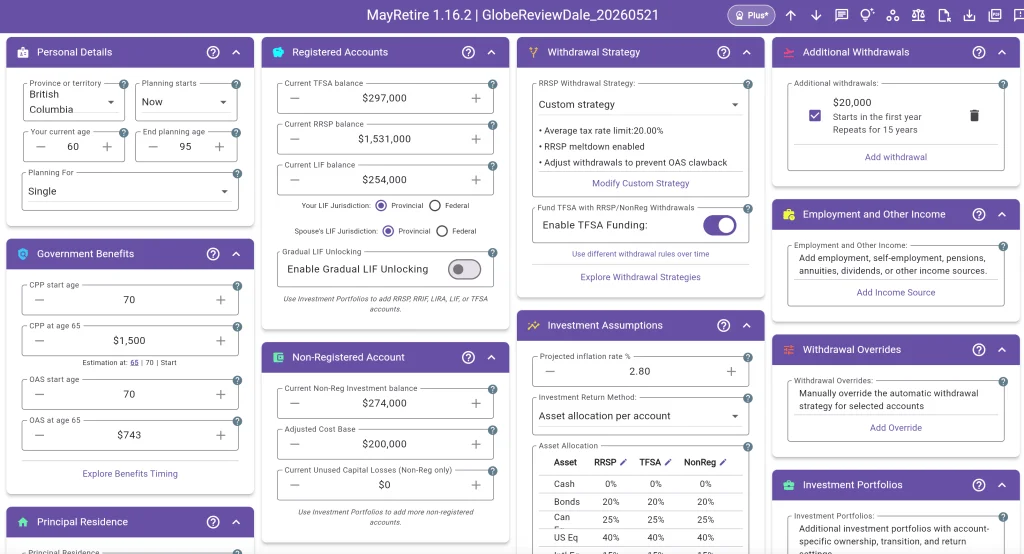
Herman is single, has recently retired, and wants to draw a strong income while limiting taxes and the potential recovery of Old Age Security (OAS) payments later. He plans to delay Canada Pension Plan (CPP) and OAS benefits until age 70. Leaving a large estate isn’t a priority, and he hasn’t set a specific retirement spending target.
His assets total $3,036,000: a mortgage-free home worth $500,000; $180,000 in bank accounts; $274,000 in non-registered mutual funds; $297,000 in a tax-free savings account (TFSA); $1,531,000 in a registered retirement savings plan (RRSP); and $254,000 held in cash in a registered retirement income fund (RRIF). The RRSP and RRIF make up most of his investable assets, so the timing and size of taxable withdrawals will strongly shape his income.
Use registered withdrawals to bridge the years before benefits
One proposed starting point is to withdraw $75,000 a year from the RRIF. Those withdrawals count as taxable income. Herman would also report interest, dividends and realized capital gains from his non-registered investments; estimated at $17,000, that brings his annual taxable income to about $92,000.
The planner’s estimate for this scenario puts Herman’s combined federal and British Columbia marginal tax rate at 28.2% and his average tax rate at 15.5%, as long as income stays below $100,000. The gap leaves some room for gains from selling investments. These are estimates for the example, not a personal tax calculation.
After tax, the $75,000 withdrawal would provide about $60,500 a year, or roughly $5,000 a month—close to the lifestyle spending level used in the plan. The proposed approach is to keep most registered assets in the RRSP and transfer smaller amounts to the RRIF over time. The RRSP and RRIF both offer tax-deferred growth, while the RRIF is suited to regular withdrawals. Keeping the accounts split also gives Herman more control over RRIF withdrawals before required minimums apply.
That flexibility has a time limit. The planner’s strategy is intended for the years before age 71, when the RRSP assets must be moved into a RRIF. Minimum withdrawals would then apply in the following year. The example estimates that a 5% average annualized return would allow the RRIF to maintain its value until age 72, when larger minimum withdrawals begin to draw it down. Actual returns will vary, so that projection is an assumption rather than a promise.
Make room for spending and future tax changes
Herman could also transfer $7,000 a year from non-registered assets to his TFSA, as proposed in the plan. That would add to his TFSA savings, while the registered withdrawals and investment income would still need to be included when estimating his taxes.
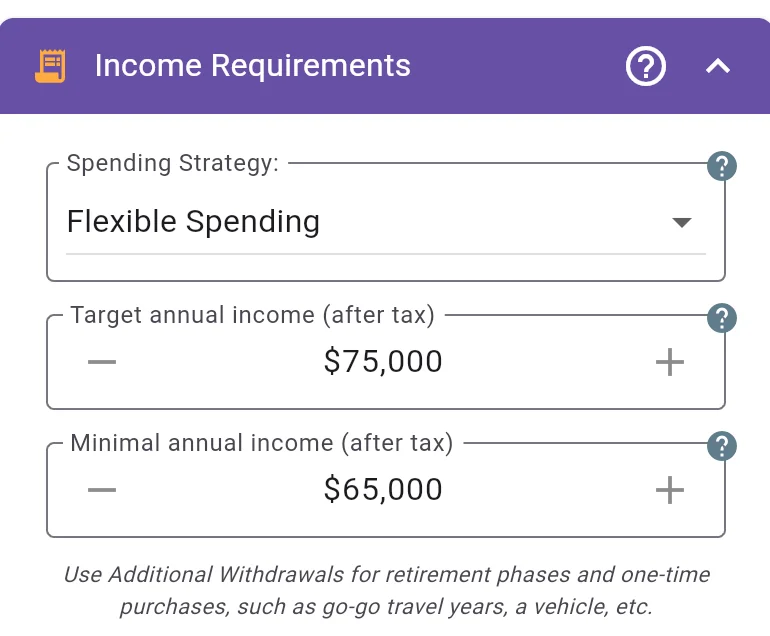
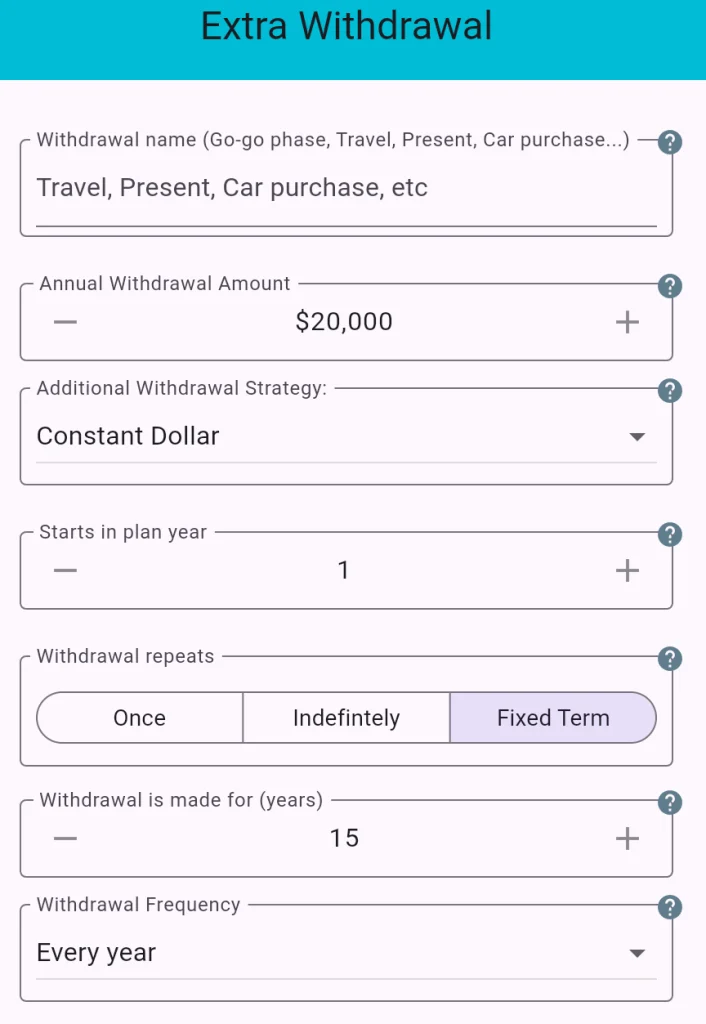
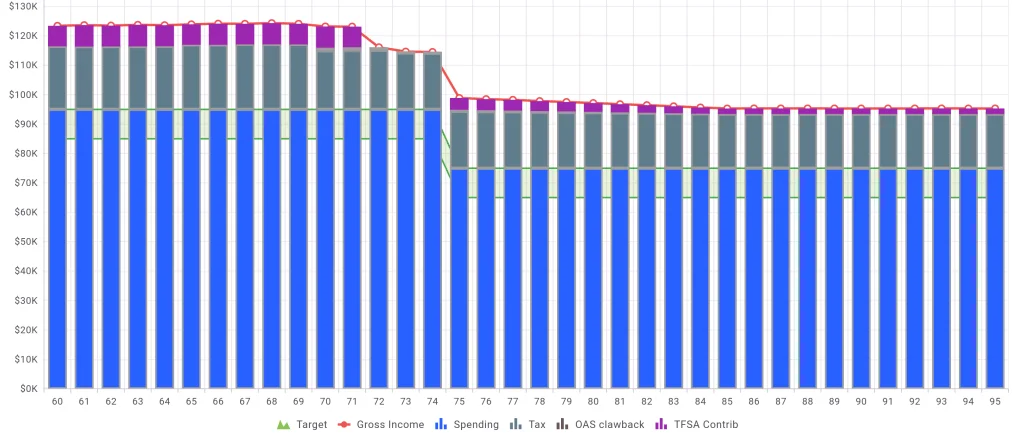
The planner sees room for more spending because Herman’s non-registered portfolio generates income whether or not he spends it. The suggested additional amount is about $20,000 a year, funded from portfolio income. A separate cash flow illustration takes this further: it starts with $75,000 of after-tax annual income, then adds $20,000 for the first 15 years of retirement, bringing spending to $95,000 after tax during that period. Afterward, the plan returns to the $75,000 baseline.
That stepped approach reflects a common way people think about retirement: spending may be higher during active early years, ease during a quieter stretch, and rise again if health or personal care needs increase. A useful plan lets someone model both recurring spending and one-time expenses, then see how they affect withdrawals and balances.
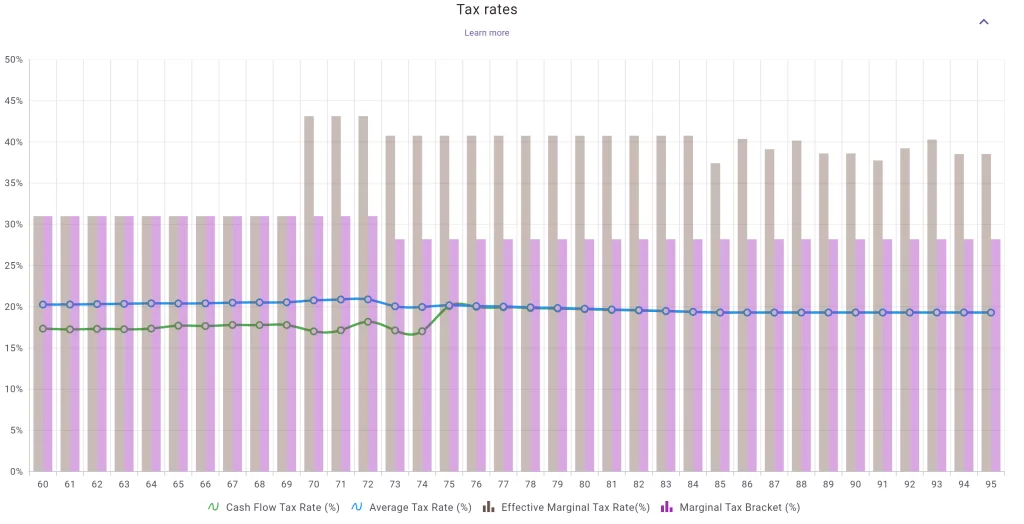
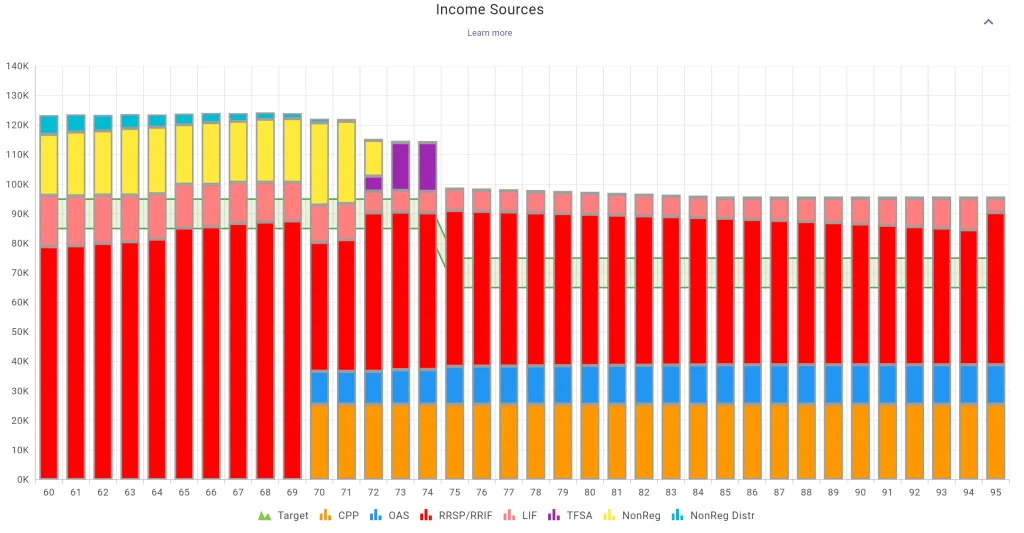
The illustration also delays CPP and OAS until age 70, using RRSP, RRIF and taxable assets to supply income in the meantime. In the planner’s estimate, once minimum RRIF withdrawals begin in 2038, total withdrawals rise to about $100,000 a year. At age 72, combining the full RRIF minimum with enhanced CPP and OAS brings gross income to about $145,000. That estimate corresponds to a 38.29% marginal tax rate and the recovery of roughly one-third of OAS.
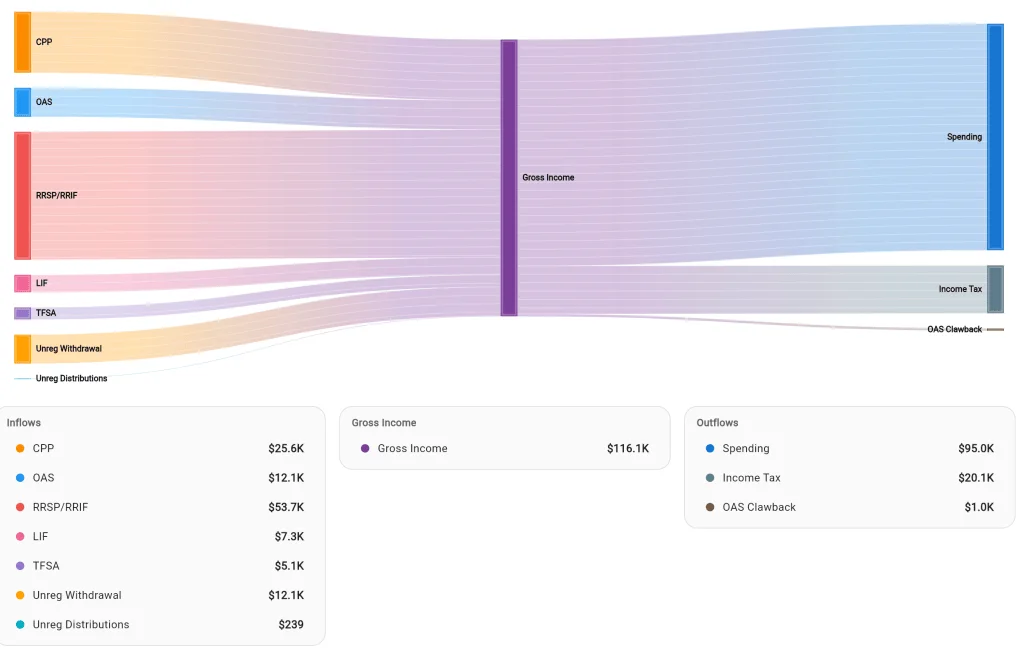
Drawing down registered savings earlier can help spread taxable income across retirement and may reduce the chance that large withdrawals later overlap with pension benefits. But the trade-off is that taxes are paid sooner, and the right balance depends on spending needs, investment income and future account values.
Read projections as a model, not a forecast
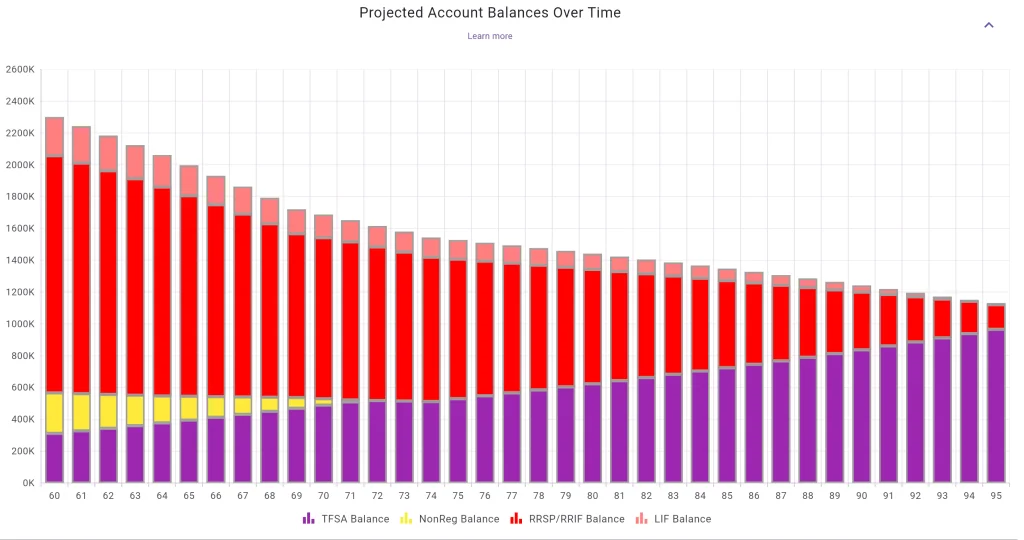
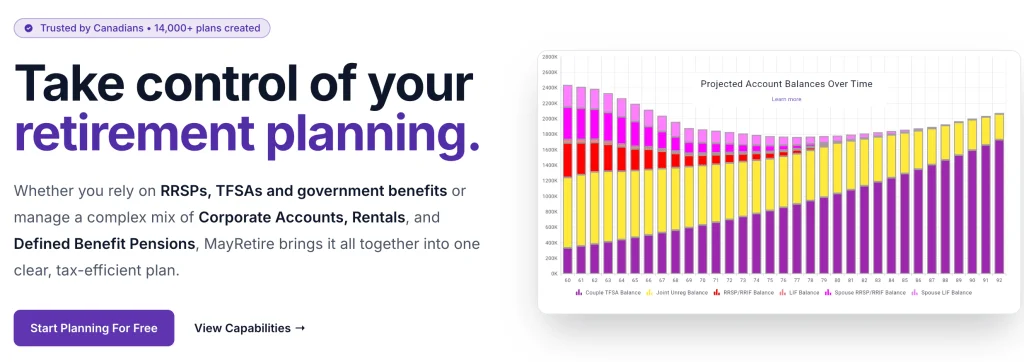
The cash flow illustration uses consistent, or “linear,” investment returns based on an assumed asset allocation. Under that scenario, non-registered assets provide part of the early income bridge and are depleted by age 73. RRSP and RRIF assets also contribute in the first decade, while CPP and OAS later provide a larger share of income.
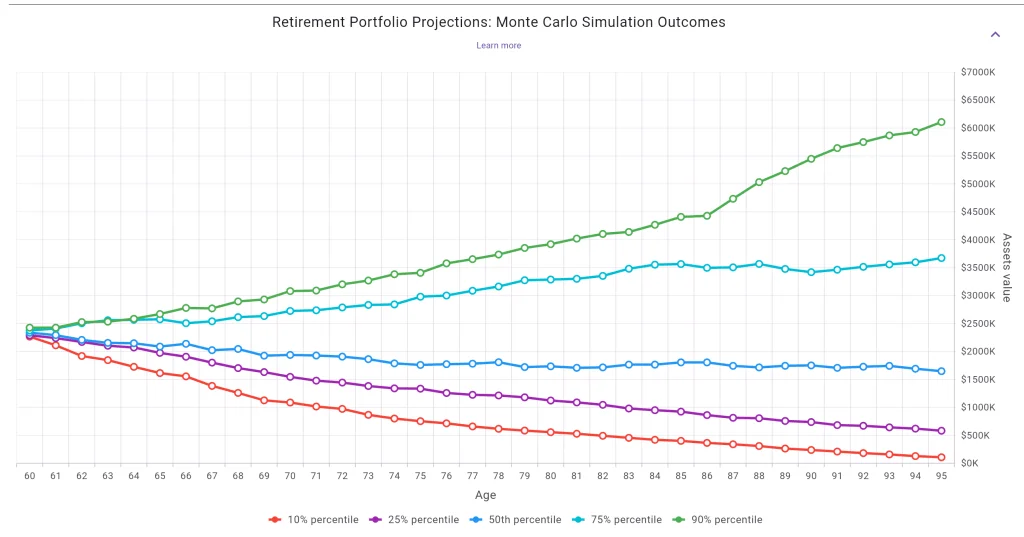
Real portfolios don’t earn the same return every year. Market ups and downs can change the order and size of withdrawals, so the smooth chart is useful for understanding the plan’s mechanics but can’t predict the path balances will take. The example also aims to smooth taxable income over time, rather than allowing large RRIF withdrawals to stack on top of increased CPP and OAS payments.
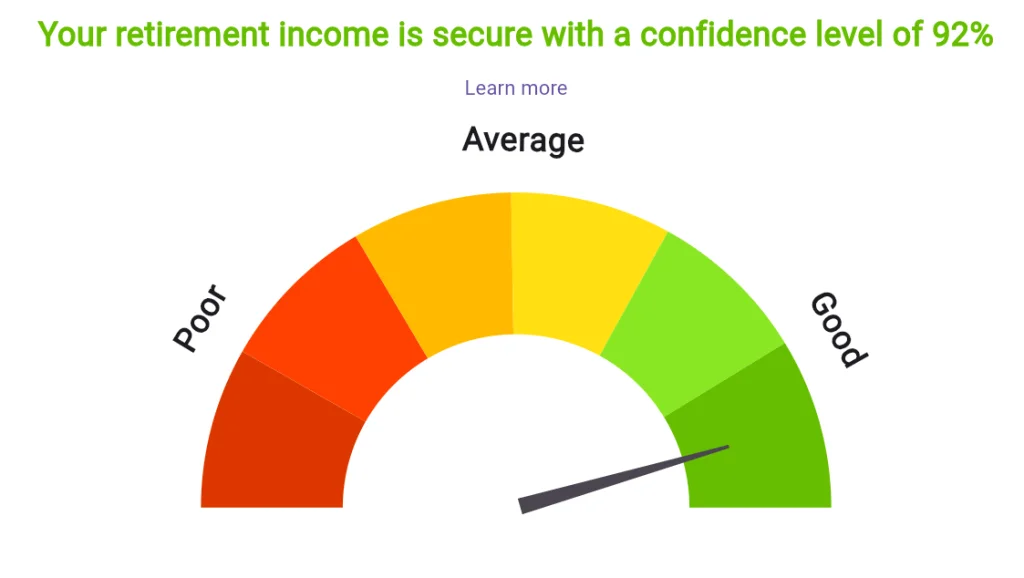
The plan was assessed through 500 Monte Carlo simulations and reported a 92% success rate. That figure describes the model’s results under its chosen assumptions. It doesn’t guarantee that the plan will work in real life; different returns, spending or longevity assumptions could produce a different result. Stress tests are most useful when they show which assumptions matter and where a plan may need adjustments.
Keep the plan connected to real priorities
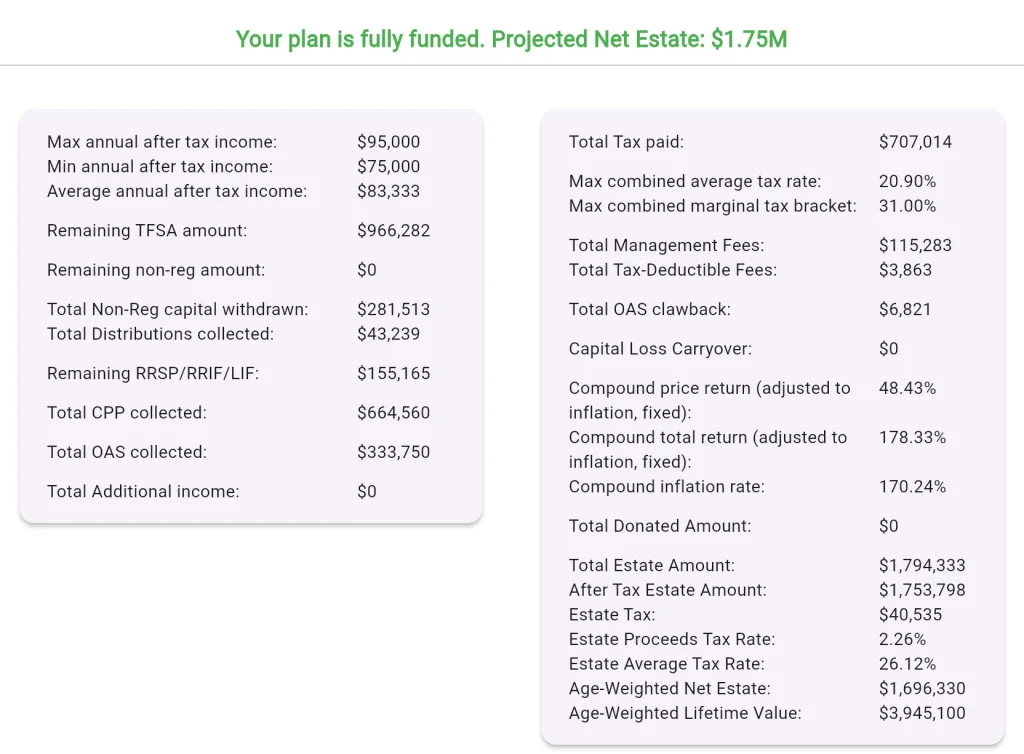
Based on the spending assumptions and portfolio size, Herman’s net worth is projected to grow. If leaving a small estate remains his goal, the plan suggests he could consider higher spending or gifts to family while he’s alive. Those are personal choices, and the projections can help frame them by showing how each change affects future income and assets.
The practical takeaway is to build a year-by-year view of income sources, taxes, spending and account balances, then revisit it as circumstances change. For Herman, the key decisions are how much to spend in the early years, how quickly to draw registered savings, and whether delaying CPP and OAS fits his needs. A useful cash flow plan makes those trade-offs visible, while keeping market uncertainty and future care costs in view.