Three UK Companies That Show Why Neglected Shares Can Draw Value Investors
Earning & Side Hustles Kartik Kumar 359 reads
Frasers, Barratt Redrow and Ryanair illustrate different routes to value, from cost control to land assets. Each also carries risks investors should weigh.
When investors focus on a fashionable theme, established businesses can receive less attention. That can create opportunities for value investors, but a low share price alone doesn’t show that a company is worth more. The case depends on what the business owns, how it competes and whether its leaders can turn those strengths into lasting returns.
Artificial intelligence is attracting excitement, while many British companies have been neglected. The potential for AI to change industries is real, but the importance of a technology doesn’t guarantee that investors in it will profit. Railways transformed transport, yet many people who financed railway ventures lost money. The broader lesson is that a promising idea and an attractive investment are not the same thing.
Three companies illustrate how a value-oriented investor might assess established businesses: retailer Frasers, housebuilder Barratt Redrow and airline Ryanair. The points below describe the investment case presented for each. They aren’t a recommendation to buy or sell shares; company prospects and share prices can change, and each business faces risks.
Frasers: retail built around cost discipline
Frasers Group (LSE: FRAS) began as a single sports shop and grew into a large retailer with brands including Sports Direct and Flannels, alongside other businesses it owns or has partnered with. Its appeal to value investors rests on two claims: it can operate at lower cost than rivals, and it adapts as customers’ preferences change.
Low costs can give a retailer room to offer competitive prices while still earning profits. Frasers’ approach also involves trying new ideas, expanding the ones that work and dropping those that don’t. That ability to adjust matters in retail, where customer tastes and shopping habits can shift quickly.
The less favourable view is that Frasers remains exposed to the challenges facing retail, including pressure on physical shops and the need to keep its brands relevant. A company that has adapted well in the past still needs to execute in the future. Investors weighing the case can look at whether cost advantages persist, how its different brands perform and whether its expansion continues to add value.
The bullish interpretation is that the company should be judged as a manager of capital as well as a retailer. Its history stretches back 40 years, and its supporters argue that its willingness to change has helped it compound capital over time. That record may inform expectations, but it can’t ensure future results.
Barratt Redrow: land, homes and the building cycle
Barratt Redrow (LSE: BTRW) is described as Britain’s largest housebuilder. The case for the business starts with housing demand: homes meet a basic need, and decades of undersupply have left the country short of them. Yet builders are still exposed to the housing cycle, construction costs and the prices at which they can sell homes.
The investment argument puts particular weight on how housebuilders buy and develop land. Builders acquire plots, construct homes and set sale prices with the aim of preserving a margin after building costs. When conditions weaken, lower land prices can help restore that margin. This framing suggests that landowners absorb much of the cycle’s pressure, supporting steady cash returns for builders. In practice, the timing and price of land purchases, build costs and sales all affect what a builder earns.
Barratt is said to have about £6 billion invested in land and homes, while its market value is around £4 billion. The managers behind the case estimate that building on the land it owns and returning the resulting cash to shareholders could deliver close to three times the company’s current market value. That is an estimate, not a guaranteed outcome: it depends on the value realised from the land, the cost and pace of construction, and the amount of cash ultimately available to return.
The company’s board has begun buying back shares with excess capital. When a business repurchases shares, each remaining share represents a larger portion of the company. That can benefit shareholders if the shares are bought at an attractive price and the company retains enough resources for its operations. It doesn’t, by itself, close the gap between an estimated asset value and the market price.
Ryanair: a low-cost model under pressure
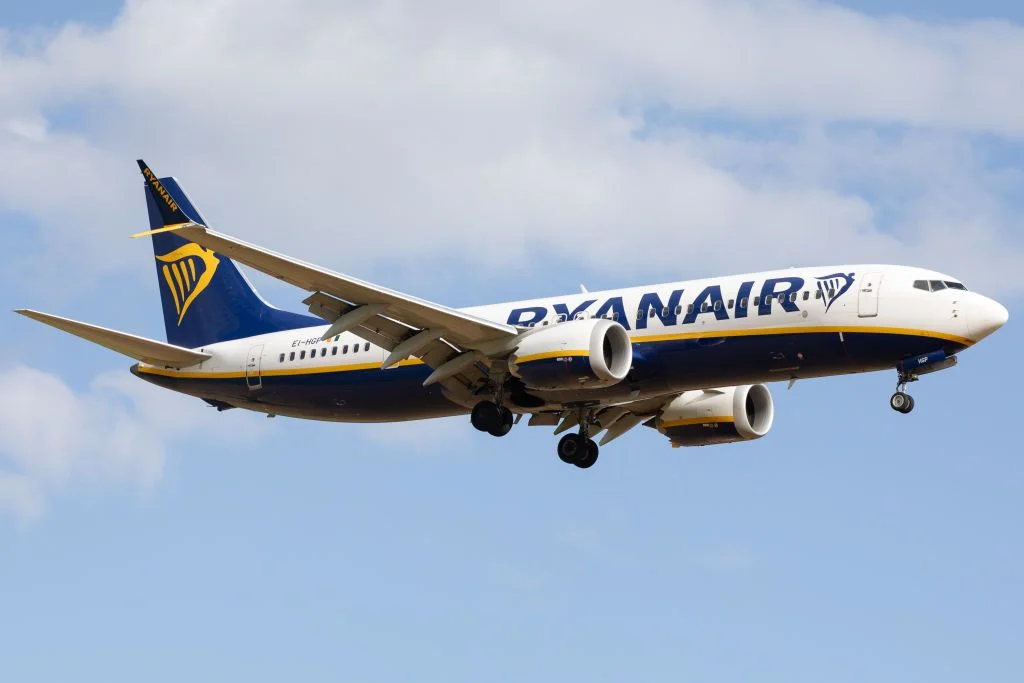
Ryanair (Dublin: RYA) carries more than 200 million passengers a year, more than any other airline in Europe. Its approach, associated with chief executive Michael O’Leary over four decades, is to keep costs low and fares below those of rivals. The airline uses one type of aircraft, aims to turn planes around in minutes and avoids paying for extras it believes passengers won’t value.
A focused fleet and fast turnarounds can help control operating costs. Ryanair’s supporters argue that competing airlines have copied parts of the model over the past 30 years without matching its cost position. The counterpoint is that airlines remain exposed to fuel prices and other pressures, while a low-fare strategy leaves little room for cost increases that can’t be offset elsewhere.
Ryanair’s shares fell by a fifth this year amid concerns about oil prices. The investment case holds that the airline has come through past aviation shocks, including the September 11 attacks and the pandemic, with a larger market position. Its low costs may help it keep flying when rivals cut capacity and give it the chance to buy aircraft when other airlines can’t. That pattern is part of the argument, not a promise that the next difficult period will play out the same way.
What the three cases have in common
Each company’s appeal is tied to a specific business feature: Frasers’ cost discipline and adaptability, Barratt Redrow’s land and homebuilding assets, and Ryanair’s low-cost operations. Those features help explain why some investors may see value where the wider market sees risk or limited growth. They also point to the questions that matter most: Can the advantage endure, can the company turn it into cash, and does the share price already reflect that potential?
For anyone assessing these businesses, the estimates and claims are starting points for research, not conclusions. A value case is only as strong as its assumptions about future trading, costs and the worth of company assets. The useful takeaway is to examine what supports the valuation, what could weaken that support and how much uncertainty remains.


