Japan's Stock Market Is Quieter, but the Numbers Still Stand Out
Budgeting & Saving [email protected] (Alex Rankine) 307 reads
Japanese shares have slumped and the yen keeps weakening, yet earnings growth and valuations are drawing a closer look from global investors.
Korean chip stocks have grabbed most of the attention this year, but Tokyo has quietly become one of the more interesting places to find AI-linked exposure. Global investors have arguably ranked it third for this theme, behind New York and Seoul, thanks to a group of companies that includes Kioxia, Tokyo Electron and Softbank. The cluster is a big reason the market matters to anyone thinking about the AI trade, even if Japan rarely makes the headlines.
The backdrop has been bumpy. Japanese shares roughly doubled between the start of 2023 and now, helped by corporate governance reforms that pushed companies to treat shareholders more seriously. That rally has run into resistance as investors start asking harder questions about how much future growth the AI boom can actually deliver.
Why the recent sell-off hit so hard
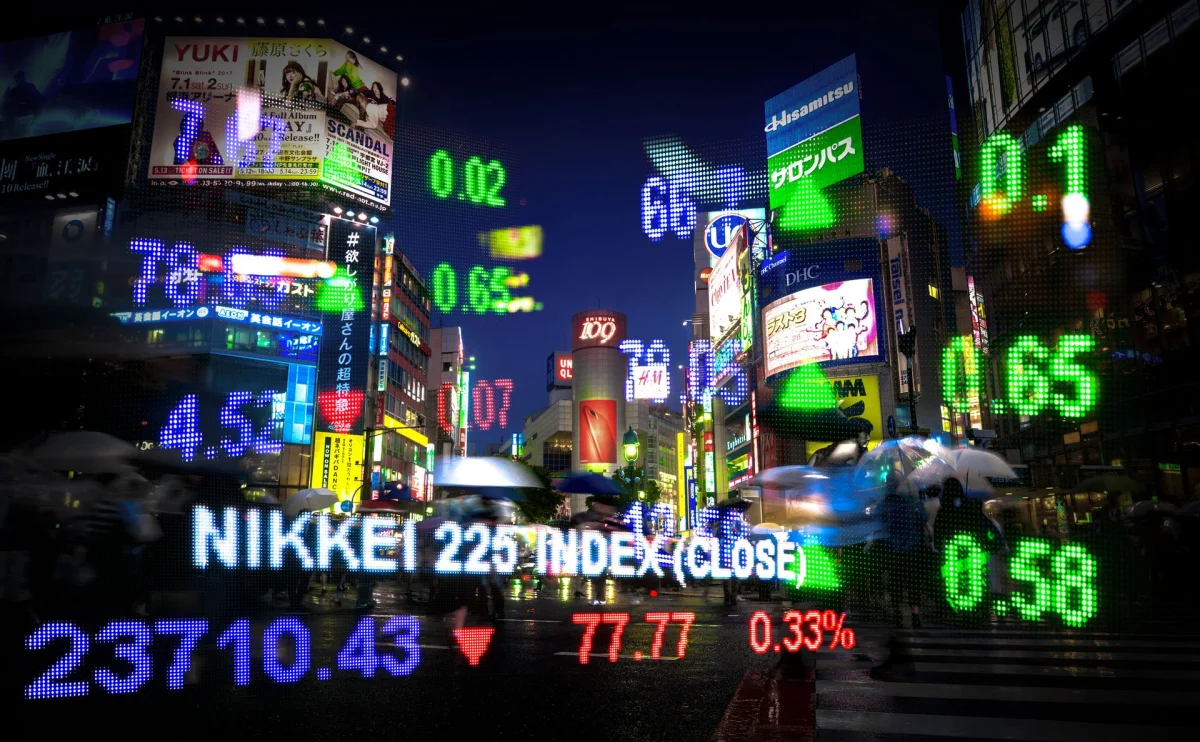
Japanese stocks slumped after the latest US political results. The concern was practical: new hurdles to data-centre construction in the US could slow the spending that many AI-linked companies depend on. The Topix index fell nearly 6% in a single day, its worst session since April of last year. The Nikkei 225 then entered a bear market, down 20% from its June peak.
That kind of move tends to rattle investors who bought into the story late. It also shows how tightly Tokyo's technology names are tied to sentiment in the US. When the AI trade wobbles in America, Japanese shares feel it quickly, even when the underlying businesses are operating as normal. My read is that this sensitivity is the price of owning a market with so many AI-geared companies.
Still, the damage has not erased the year's gains. The Nikkei has climbed almost 14% since 1 January. Leo Lewis, writing in the Financial Times, argues that Japanese stocks could still finish the year "among the strongest performers in the world". That's a bold claim after a sharp drop, and it's worth treating as one commentator's view rather than a forecast.
One detail stands out. Outside the US, Tokyo offers the widest range of shares with a reasonable claim to AI exposure. Even toilet makers and table seasoning producers in Japan list "high-tech subsidiaries", which tells you how far the theme has spread into unlikely corners of the market. Spread like that can cushion a portfolio, but it can also hide how much of the market depends on a single idea.
The yen question
For foreign investors, the currency is often the bigger headache. The yen has lost about a quarter of its value against the pound over the last five years, which means a gain on a Japanese share can shrink or vanish once it's converted back to sterling. Anyone who bought Japanese equities without thinking about currency may have been surprised by how much the exchange rate has taken out of returns.
A large intervention over the summer temporarily reversed the trend. The cost was significant: the central bank spent currency reserves equal to 2.4% of GDP. Now, according to Cole Lipsky and John Cheng writing for Bloomberg, the central bank appears to be ready to use that tool again. One analyst described the intervention as a "defibrillator" that can be charged back up when the yen moves too far.
There's a longer-term angle, too. Japan's native population is shrinking by around 100 people an hour, and a weaker yen may be part of the adjustment for a country in that position. That said, a soft currency is not a neutral thing for households and investors. It makes imports more expensive and can wear on savings held in yen, so it's a trade-off rather than a simple benefit.
The yen's safe-haven role has also weakened. Traditionally, it's been an asset that gains when markets are under stress. Lipsky and Cheng note that it held up better than expected during last month's technology stumble. The dollar, which many investors treat as their default safety blanket, has become so tied to AI-trade swings that the yen stands to look comparatively steady when that trade falters. In a shaky moment, that kind of relative strength can matter more than the yen's long-run trend.
Earnings and valuation
Underneath the price moves, earnings look more solid than the sell-off suggests. Asset Management One International (AMOI) describes recent corporate results as "solid". Consensus forecasts point to earnings growth of 17.5% for the 2026 fiscal year and 11.4% for 2027. Those forecasts cover a broad mix of industries, including carmakers, financial firms, trading houses and chemicals companies, so the growth isn't coming from one or two names.
Oleg Kapinos of AMOI makes a point that stands out. Japanese firms are increasingly passing higher input costs on to their customers. That's a departure from the deflationary habits that held back Japanese companies for years, when raising prices was seen as risky. Being able to pass on costs is one reason profit margins have held up, and it's a change worth watching. It's also the kind of shift that doesn't always show up in headline numbers.
Valuation is where the case gets most interesting. The Tokyo Prime market trades on a price-to-book ratio of 1.6. The S&P 500's equivalent figure is above five. Kapinos sees "clear value" in that gap. A lower price-to-book ratio doesn't guarantee better returns, since cheap markets can stay cheap for years, but it does explain why some investors are looking at Japan again.
Who this kind of picture suits, and who it doesn't
This isn't a straightforward buy signal, and it's not general investment advice. Japanese equities carry a few distinct risks: sensitivity to AI sentiment in the US, exposure to currency moves for anyone not investing in yen, and the possibility that cheap valuations stay cheap. Investors who can tolerate sharp swings and who already understand how currency affects their returns are in a better position to weigh the case. Anyone who needs their money in the short term, or who is uncomfortable with a single theme driving a chunk of a portfolio, may find the volatility harder to live with.
What to watch next is fairly clear. Keep an eye on whether the AI-linked names recover as the US data-centre debate plays out, whether the yen steadies or the central bank steps in again, and whether Japanese companies keep passing costs on to customers without losing volume. Those three threads will do more to shape the next few months than any single headline.